Make a number hard to read.
The question: can uncertainty stay visible instead of becoming a confident mortgage fact?
 Velocity
MORTGAGE-FILE REVIEW
Review the values. Inspect the evidence.
Keep the lender in control.
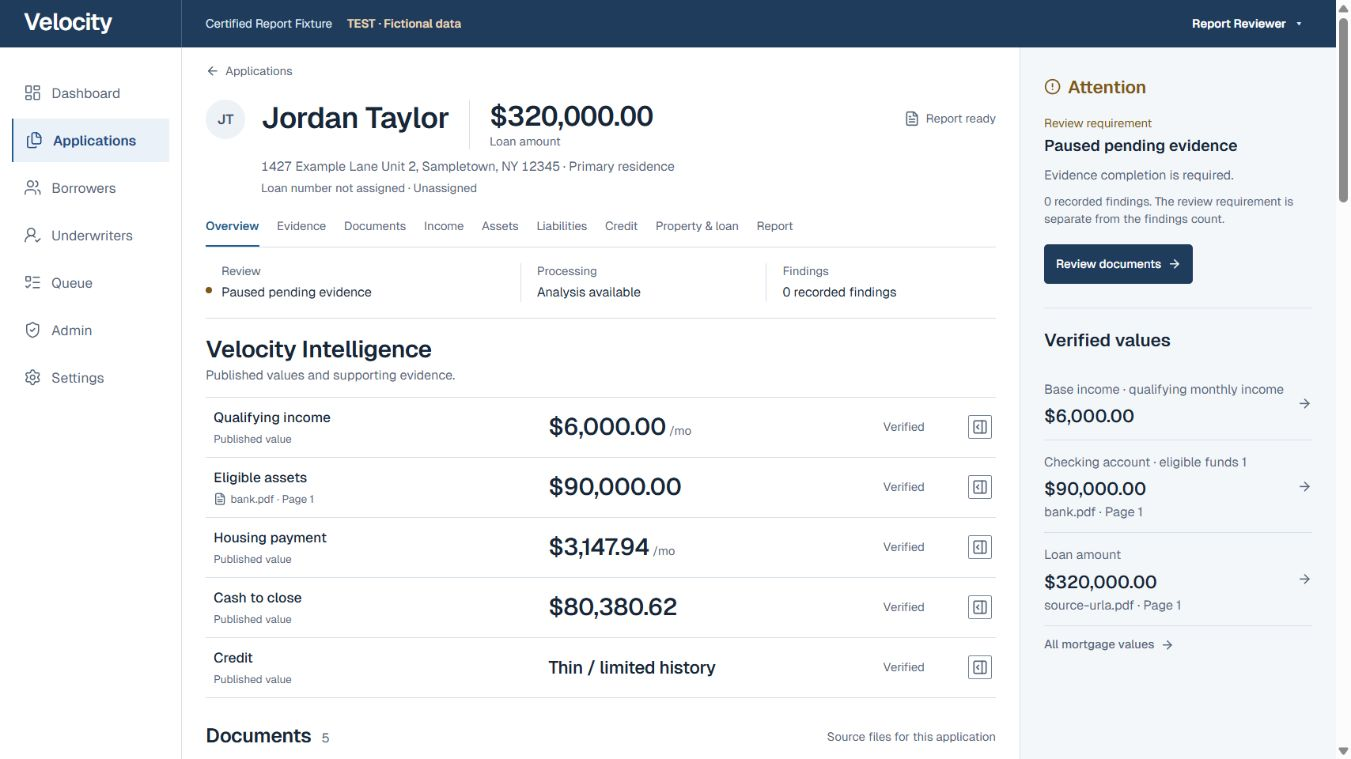
Native product capture, not a live application. The lender retains credit-decision responsibility.
A beginning balance and an ending balance can both be read correctly. That still makes them one account—not two sets of funds.
Velocity keeps published values connected to the borrower, account, source page and available supporting observations. Missing support and meaningful disagreement remain part of the review.
One account.
Preserve the meaning.
Illustration uses balances shown in the fictional evidence capture. It is not a lending calculation.
02 / INSPECT THE SUPPORT
Who does it belong to?
Which account?
Which document and page?
The available evidence stays in context. When detailed calculation treatment is unavailable in a view, the product says so. Source confidence is not lending eligibility.
See the evidence view →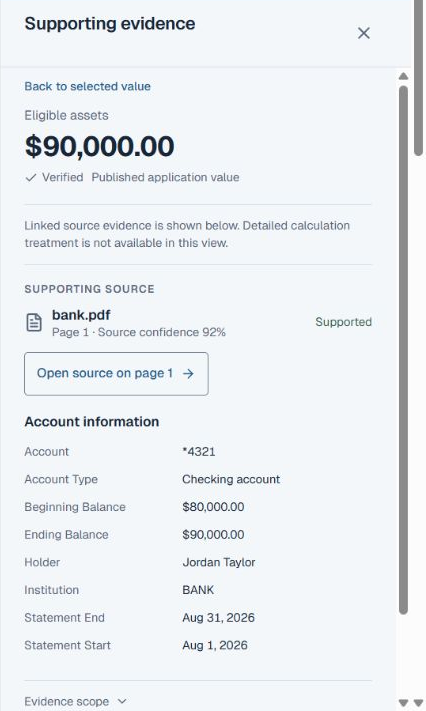 ACTUAL TEST CAPTURE · FICTIONAL DATA
03 / TEST THE MORTGAGE MEANING
Our internal testing story is organized around the mistakes a reviewer needs a system to resist—not just whether it returns an answer.
The question: can uncertainty stay visible instead of becoming a confident mortgage fact?
The question: can repeated observations be kept distinct from separate income streams?
The question: can newer information become current without hiding history or false completion?
Discuss the case definitions, expected results and reported outcomes during evaluation. Internal testing is not SOC 2, an independent penetration test or a guarantee about every future file.
04 / A CONTROLLED WAY TO START
Start with a fictional demonstration. Authorize the data boundary before any historical or live borrower files. Then compare the results with files your team already understands.
Name reviewers, reference answers and acceptance criteria.
Review data, providers, access and the actual deployment.
Record correctness, coverage, evidence and reviewer effort.
Stop, repair or authorize a bounded next phase. No automatic rollout.
Your lender workflow stays authoritative. Named LOS integrations and customer-specific infrastructure are separate scope.
05 / BEFORE THE FIRST FILE
No. Velocity supports mortgage-file review. The lender retains underwriting, policy application and credit-decision responsibility.
Not in this frozen version. Permitted members share loan visibility inside their lender workspace. Assignments organize work; they do not create private portfolios. The pilot must fit your access policy.
Only after the required data and deployment approvals. Historical files are still borrower data. The first demonstration can use fictional files instead.
No completed named LOS write-back, independent security certification or guarantee of continuity during another vendor’s outage is being promised. Integration and operating requirements are agreed for the specific scope.
LET’S START WITH THE REVIEW
A conversation about the workflow.
No borrower documents needed.
Preview only: this button prepares a draft. It does not submit or send anything.
Do not include borrower names, account numbers or source documents in an introduction.